

 Legal updates
Heritage property and IHT: understanding Conditional Exemption
8 Oct 2026
5 min read
This website will offer limited functionality in this browser. We only support the recent versions of major browsers like Chrome, Firefox, Safari, and Edge.
Legal updates
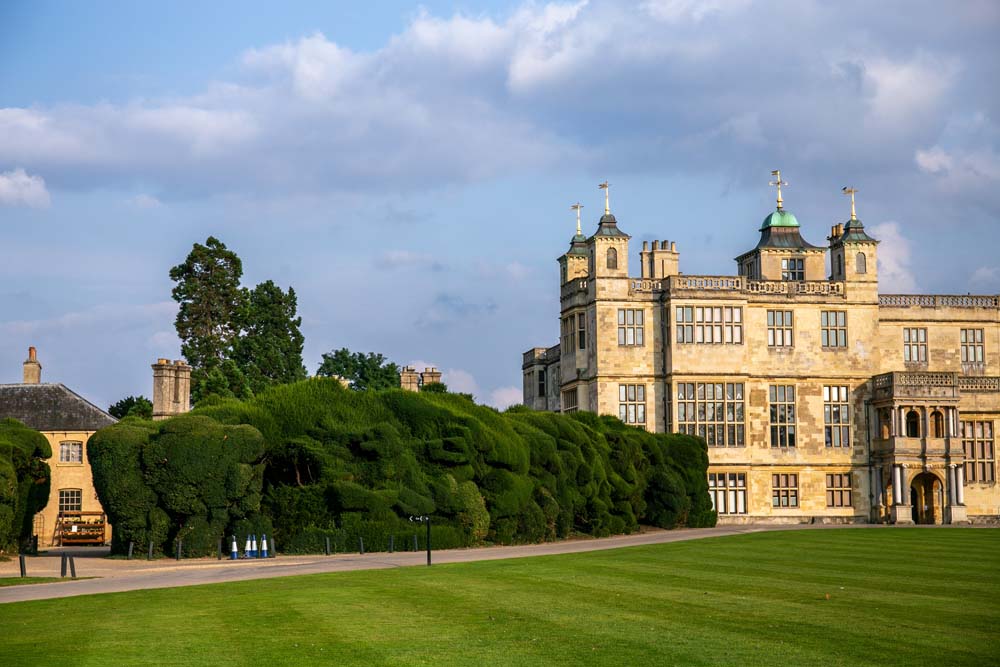
With recent changes to the availability of Agricultural Property Relief and Business Property Relief, there has been a renewed interest in the conditional exemption from inheritance tax (“IHT”) for heritage property.
Heritage property can include:
These categories are set out in the IHT legislation.
The purpose of the Heritage Property regime is to encourage owners to preserve and share the country’s heritage with the public by providing IHT incentives.
The three main types of relief are:
In this post, we consider Conditional Exemption with future articles looking at the other two.
Conditional Exemption allows the payment of IHT to be deferred on occasions when it may arise, such as chargeable lifetime transfers (e.g., transfers to trusts) or on an owner’s death.
If the claim is accepted by HMRC, no IHT will be due at the time of the transfer. This is a deferral rather than a relief and the IHT may then arise in the future on an open market sale of the property, a breach of the conditions attached to the exemption given, or if the undertakings are not replaced by a new owner (such as when property is transferred by way of gift).
To claim Conditional Exemption, the owner needs to demonstrate to HMRC that the property on which the IHT is due qualifies as Heritage Property, agree public access requirements, and the ongoing management requirements for the property.
A heritage management plan will be produced to set out the basis for the claim, the significance of the asset and its history, detailed surveys, an agreed programme of maintenance and preservation, as well as details of the public access requirements.
Specialist advice given by heritage advisors is usually taken at this stage to help prepare this document and agree its terms with HMRC.
HMRC on their part will consult specialist bodies, such as Arts Council England, Historic England, and Natural England who will inspect the property, advise HMRC, and make recommendations as to whether the property qualifies and, if so, the ongoing obligations that should be sought.
Any exemption obtained is conditional. The owner must give an undertaking to HMRC covering three main obligations to benefit from the exemption:
While the above covers the general position, each undertaking agreed on a case-by-case basis.
Depending on the nature of the transfer, it is often possible for conditionally exempt property to pass to a new owner without the deferred IHT becoming due. This requires the new owner to sign up to the existing undertakings with HMRC.
In cases where on the transfer to the new owner there would otherwise be an IHT liability (such as on death), HMRC may reassess the property and the undertakings may be updated or renegotiated.
In this way, heritage property can therefore usually continue to be exempt from IHT so long as the conditions are maintained and the property continues to qualify.
If the property is sold on the open market or the undertaking is otherwise breached, the deferred IHT will become payable. The charge will be based on the value of the property at that time.
Consideration should also be made if the heritage property has earlier exemptions from previous IHT regimes or Estate Duty (or more unusually Capital Transfer Tax), and how those historic exemptions may interact with each other.
Conditional exemption will be an attractive route for some owners of heritage property, following the reduced availability of agricultural property and business property reliefs. That said, owners should be alive to the ongoing obligations, in particular public access, that will be required of them to obtain the exemption.
Our private wealth team has extensive experience of advising owners of heritage property, applying for and maintaining conditional exempt status as well as wider advice to landed estates owners of significant collections of artwork as part of their tax planning and succession planning.

 Thought leadership
6 October 2026
Podcasts
1 October 2026 • 10 min read
Thought leadership
28 September 2026
Thought leadership
24 September 2026
Legal updates
9 September 2026
Want more Burges Salmon content? Add us as a preferred source on Google to your favourites list for content and news you can trust.
Update your preferred sourcesBe sure to follow us on LinkedIn and stay up to date with all the latest from Burges Salmon.
Follow us