

 Thought Leadership
Repowering Onshore Wind: Opportunity, Urgency and the Challenge of Delivery
22 Sep 2026
3 min read
This website will offer limited functionality in this browser. We only support the recent versions of major browsers like Chrome, Firefox, Safari, and Edge.
Thought Leadership
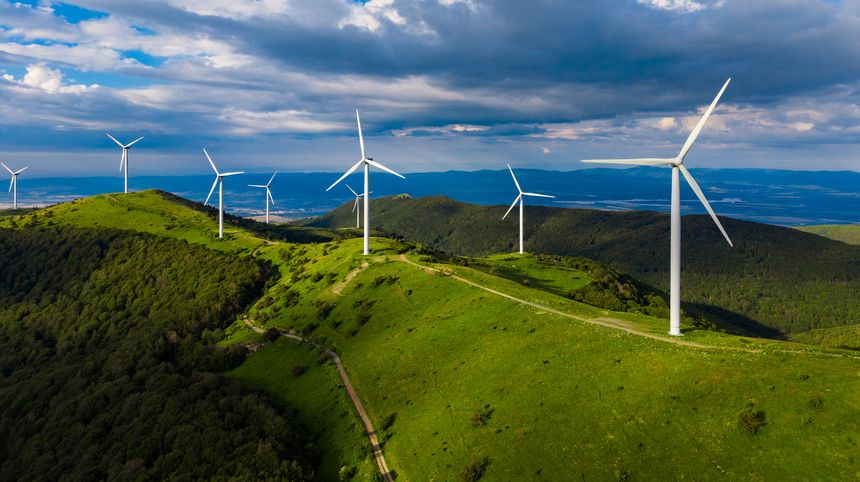
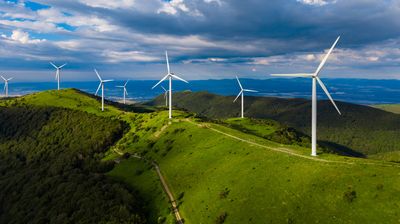
The UK’s onshore wind fleet — one of the country’s greatest energy success stories — is approaching a critical juncture. Recent discussions featuring developers, consultants, energy analysts and legal practitioners at industry showcases have underlined the growing case for repowering existing wind farms, and the barriers that must be overcome if the opportunity is to be realised.
There is broad consensus across the onshore wind sector that ageing onshore wind sites should be viewed not simply as legacy infrastructure, but as strategic energy assets. These are locations with established grid connections, existing land agreements, operational track records and longstanding community relationships. Industry analysis suggests that by 2035, more than half of the UK’s onshore wind fleet will be approaching a repowering decision, with the potential to unlock between 2GW and 6GW of additional capacity by 2050.
The urgency is real. Major developers have noted that around half of their onshore portfolio will reach end of life within the next decade, and that subsidy support for a significant proportion of assets expires as early as 2027. Without a clear pathway to repowering, some projects risk becoming loss-making, leaving operators to choose between decommissioning, operating at a financial loss, or abandoning repowering plans altogether.
The dominant concern raised during recent discussions has been grid access. Several participants in panel discussions have highlighted that existing wind farms have been excluded from current grid queue arrangements, leaving developers unable to plan with confidence. Existing grid connections are predicated on the type and scale of equipment originally installed. Following any significant repowering, the network operator will be phased with a decision as to whether the existing connection agreement needs updated or replaced. Without clarity on that process, unlocking the potential benefits of repowering gets more difficult - the supply chain cannot mobilise, decommissioning cannot proceed in an orderly fashion, and the wider repowering opportunity may be lost.
Importantly, industry figures in recent months have challenged the assumption that repowering must always mean a complete replacement of existing equipment. In fact, there are partial repowering and component refurbishment strategies that can extend operational life and improve energy output without requiring new grid connections or major planning consents. The message is clear: developers should assess what is achievable within existing constraints rather than waiting for a perfect solution.
From a financing perspective, it has been noted by those in the field that lenders and insurers are primarily concerned with whether remaining useful life, performance expectations and risk profiles can be demonstrated with confidence — regardless of whether components are new or refurbished.
On the planning front, there is a growing feeling that while national policy frameworks in both England and Scotland are broadly supportive of repowering, the fact that existing consenting and policy regimes were not originally designed with repowering in mind means challenges remain. Crucially, industry participants have identified proportionate environmental assessments and pragmatic regulatory guidance as key to unlocking progress.
The importance of end-of-life planning has also been highlighted. The onshore wind sector has been urged to develop domestic capabilities for refurbishment, remanufacturing and recycling, rather than relying on international supply chains.
A common theme in the various interventions regarding repowering in recent months is agreement that the practice represents one of the fastest and most practical routes to increasing UK renewable generation, but that the supporting systems — grid access, planning processes and investment frameworks — have not yet evolved quickly enough to match the scale of the opportunity. Decisive action, particularly on grid allocation, is now essential if the sector is to avoid losing ground at a pivotal moment in the energy transition.
If you would like to discuss the content of this article further, please contact Dixcee Fast, Mark Summers or Lauren Winters.
This article was written by Mark Summers
 Thought leadership
22 September 2026
Thought leadership
11 September 2026

Thought leadership
4 September 2026
Thought leadership
19 August 2026


Legal updates
29 July 2026
Thought leadership
29 July 2026

Want more Burges Salmon content? Add us as a preferred source on Google to your favourites list for content and news you can trust.
Update your preferred sourcesBe sure to follow us on LinkedIn and stay up to date with all the latest from Burges Salmon.
Follow us