

 Podcasts
Death & Taxes S6: E3 – Balancing UK-US Tax Considerations
27 Oct 2026
10 min read
This website will offer limited functionality in this browser. We only support the recent versions of major browsers like Chrome, Firefox, Safari, and Edge.
Podcasts
In this episode, Helen MacLeod is joined by Suzanna Harvey and Edward Hayes to explore the key private wealth considerations for individuals and families with connections to both the UK and US, including cross-border tax, trusts, double tax treaties, lifetime gifting, property ownership and estate and succession planning.
They also consider how careful planning can help navigate the differences between the two tax systems.

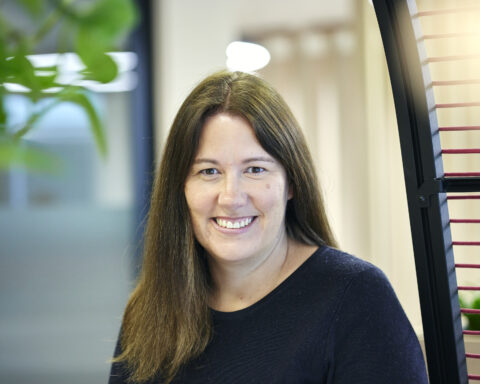
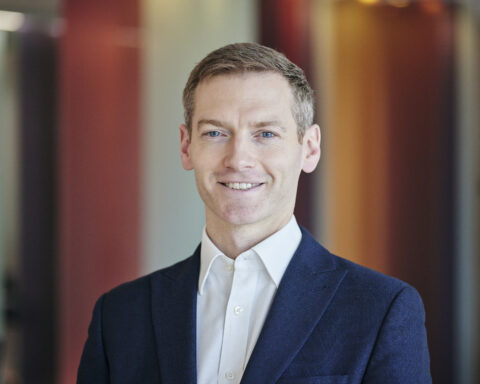
Helen MacLeod (00:00)
Hello and welcome to Death and Taxes, the Private Wealth podcast from Burges Salmon. I’m Helen MacLeod, a senior associate in the private client team, and in today’s episode, I am joined by my colleagues, Suzanna Harvey and Edward Hayes, to discuss some of the key private wealth considerations for clients with connections to both the UK and the US. Suzanna is a partner and Head of Private Wealth at Burges Salmon, and Ed is also a Partner in our private client team.
Given the historic relationship between the US and the UK, it is extremely common for clients to move from the US to the UK or vice versa, and for globally mobile families to have at least one family member who spends time living in one or both of these jurisdictions. Therefore, both Suzanna and Ed frequently advise on UK tax trusts and succession for US connected families. They work alongside trusted advisors in the US to ensure that any advice is joined up, and solutions are found that are appropriate in both jurisdictions.
Suzanna and Ed, thank you very much for joining me today. Just a flag that we are recording this podcast before the upcoming UK budget on the 28th of October. As useful as it would be, we unfortunately don’t have a crystal ball to confirm whether any tax changes will be made on that date. And so this discussion is based on the law as it currently stands. So, without further ado, it would be helpful to understand the general background to US advice to start with. Suzanna, what are the main principles on which US-UK advice is founded?
Suzanna (01:27)
Thanks, Helen. Well, I think it probably makes sense to start with a general explanation of the basis of taxation in each country because it is slightly different. So the US is actually one of the few countries in the world that tax is based on citizenship. So a US citizen is subject to tax in the US on their worldwide income and gains, regardless of where they’re resident. And it’s actually worth noting that a US green card holder is treated in the same way as a US citizen for most US tax purposes.
In contrast, in the UK, the UK taxes people based on their residence. So, a non-UK resident, even if they’re a UK citizen, generally isn’t subject to tax in the UK other than on very limited sources of UK income and gains. In contrast, a UK resident is subject generally to tax on their worldwide income and gains. It’s worth noting that your status in the UK does change, though, the longer that you’ve been living in the UK.
So, with effect from April 2025, a new regime was introduced. So, for the first four years of residence, you can benefit from something known as the four-year FIG regime. The four-year FIG regime can only apply if you’ve been non-resident for consecutive period of ten years, but for those first four years, you’re effectively not subject to tax on non-UK income and gains. Some caveats to that, but that’s the general position, and it’s a very beneficial treatment for those first four years. You do still need to report, though, all of your worldwide income and gains in your tax return. So, we find that clients do still need some professional help in considering what they’re going to report on the compliance side. But it’s still something that’s really valuable.
And then it’s also just worth noting, again, from the changes that came in from April 2025, that for the first ten years of residence, you’re known as- you’re not of what we call a long-term resident in the UK. So, a long-term resident in the UK is someone who’s been resident in 10of the previous 20 UK tax years. And whilst you are not a long-term resident, your own exposed to UK inheritance tax on your UK situated assets. Once you become a long-term resident, you’re exposed to UK tax on your worldwide assets. And it’s also worth noting that when you leave the UK and cease residence, there’s a tail period, which can be anything from 3 to 10 years when you’ll still be exposed to UK inheritance tax, in normal circumstances if you’ve been a long-term resident.
So, I think you can see from that that the systems in the UK and the US are pretty different. And we spend a lot of our time effectively trying to align tax points so you can take advantage of the double tax treaties that we’ll talk about a bit more in due course. And the situations that I think we tend to see most in practice are US citizens that are either living in the UK or considering moving to the UK, individuals in the UK considering moving to the US, or that have recently moved to the US and are within that ten-year initial period, and beneficiaries of US trusts. And they are kind of key areas that I think we end up often being asked to advise on.
Ed (04:47)
And to follow up on that, I think as Suzanna said, one of the key things we try and do, because that mismatch between how the US and the UK are seeking to tax individuals and income and gains that are being generated, we are trying to match up those tax points. So, we’re always trying to make sure that actually if you’re going to have tax in both jurisdictions at all, it’s being triggered at the same time and on the same thing. So, then we can at least get credits and avoid double taxation. Now really common examples of that going wrong if people aren’t well advised, things like grantor trusts, people in the US will use trusts for all sorts of types of planning, and those will often be seen as transparent in the US, but actually in the UK -and we’ll come onto this a bit more detail – but they’re often opaque. And if you get that wrong, you can find that actually the US is taxing one thing, the UK is taxing the other and you don’t get a credit between the two. US LLCs as well are another common example. And actually we have a- there’s a consultation at the moment and the UK is considering changing its treatment of LLCs, but for now HMRC starting position is at least that will generally be opaque for tax purposes, whereas often in the US they’re going to be treated as transparent. And again, that one jurisdiction treating something as transparent and one treating it as opaque is very common in the US-UK tax planning and trying to match that up is at the core of lots of what we do.
Helen (06:04)
That’s really helpful. Thank you both for you. I think it’s fair to say that for US-UK tax planning, the treaties are key. So, there are two treaties, the income tax and capital gains tax treaty and the inheritance tax and estate tax treaty. And both of these are relevant for both lifetime planning and for estate and succession planning. So could I ask you to give me a one-minute overview of the key things for each treaty? So Ed let’s start with the income tax and CGT treaty.
Ed (06:32)
One minute. Okay. So, it’s very like lots of other income tax and CGT treaties that you’ll see the OECD has helped prepare and that the UK has with many other jurisdictions. So, its core goal is trying to identify one of those two jurisdictions where someone is treaty resident, i.e. which is their kind of primary jurisdiction for want of a better phrase. And then generally it will try and give that jurisdiction primary taxing rights.
Now, if you just read the text of the treaty, you would think that in many cases it’s giving a sole taxing rights and saying, right, only this jurisdiction can tax this form of income or gains, but actually it should be thought of as a credit treaty, particularly because it has some quite unique saving provisions in it. And, you know, the most well known and most important to be aware of is the fact that the US is allowed to tax its citizens effectively, no matter what the treaty says. So, the treaty specifically preserves the US’s right to apply tax to its citizens. So that means actually, if you’re getting a benefit under the treaty, as someone in the UK, you are generally being allowed to clean the UK tax you pay as a credit against your US tax liability. It’s not getting rid of your US tax liability.
A really common example of the kind of relief we’ll claim is the dividend withholding relief. You know, lots of people invest into the US stock market, and lots of people will be receiving dividends from US stocks. The default withholding rate is 30%, but you can often use the treaty to claim 15%. One final point for the minute summary is, there is a Limitations of Benefit clause as well. So as well as that savings provision, the US-UK treaty has a relatively broad Limitation of Benefit provision, and you have to be very careful when looking at it to make sure you do qualify for the various reliefs that you might be able to claim underneath it.
Helen (08:20)
Great. Thank you. And Suzanna, one minute on the IHT treaty?
Suzanna (08:24)
Can it be one minute like Ed’s one minute?
Ed (08:27)
1 minute, 30?
Suzanna (08:28)
Yeah, something like that.
So unlike Ed mentioned that the income tax treaty is quite similar to lots of other treaties with other jurisdictions. It’s just worth noting that there aren’t actually that many estate tax treaties that the UK has with other jurisdictions, but the US-UK estate tax treaty is one of them. And it’s also worth mentioning that it’s probably become a lot more relevant, and we’re talking about it a lot more now in light of the April 2025 changes than we were before. So it really is a key part of our day-to-day advice now.
The overall purpose is kind of similar to the purpose of the income tax and CGT treaty, though. It’s to prevent somebody from somebody estate from being taxed in both jurisdictions at the same time without any relief. And like Ed said, I mean, there can be circumstances in the estate tax treaty where, certain assets are actually excluded from charge in one country or the other. But sometimes, again, it’s just a credit situation so that you are taxed in both jurisdictions, but with a credit. So it is worth always bearing that in mind.
The, the treaty looks to determine, so as a matter of local law, whether you’re domiciled in each jurisdiction. And again, following the changes in April 2025, a lot of people think domicile isn’t relevant anymore. But that’s not true, particularly in the context of treaties. Although it is worth noting that domicile for these purposes does include long-term resident that I talked about earlier. So, if you’re a long-term resident, you will be domiciled in the UK for the purposes of the treaty. And then the treaty does a bit like it would do in the income tax treaty. There’s sort of tiebreakers if you’re domiciled in both.
But fundamentally you can have a situation where, for a US person, say living in the UK, if they’re US domiciled, they’re only exposed to UK inheritance tax, say, on real estate and certain business assets related to permanent establishments in the UK and vice versa. But a bit like Ed mentioned, there is a citizenship savings clause. And it’s important to note that the citizenship clause in the estate tax treaties really key for both the US and the UK. So, there are circumstances where you would have got more significant relief in the UK if you weren’t a UK citizen. And so it’s something that clients need to consider seriously, US individuals moving to the UK, if they’re considering taking dual citizenship, then it is also worth considering the impact of that will have on them on the treaty.
Ed (10:54)
And it’s one of the few cases in it of actually UK citizenship impacting your UK tax exposure. It’s quite rare actually in the UK tax code.
Suzanna (11:02)
Exactly. And it goes against what I said at the very beginning where I said that we don’t have a citizenship-based tax system, but in this context, citizenship actually is really important.
Helen (11:11)
Great. And so, with that context and background in mind, let’s move on to lifetime planning considerations for US-UK clients and how these treaties can provide solutions and planning for across jurisdictional clients.
So we know that trusts are very, very popular in the US and can offer significant US advantages, but they do, as everything, need to be carefully considered for US-UK clients. So let’s dig into that a little more.
Ed (11:38)
Yeah, and I think in the suppose the first thing to stress is that in the US market, trusts are often used as a kind of a way of either minimising or avoiding probate and so forth. And they’re a very easy estate planning tool to use in the US, because you can often put them in place without tax consequences there basically. In the UK, your starting assumption should always be that a trust is going to have some tax consequences. We often get asked to advise on the treatment of US trusts. And a particular example is a grantor trust, usually see-through basically in the US. And the question we all get, well is this also going to be see-through in the UK? And if it is, that’s often actually quite a valuable outcome because we can max up the tax triggers and we can use the treaty to claim credit between the two. If it’s not transparent in the UK, so we tax it as basically, you know, an opaque or substantive trust. That’s where you have to get a bit into more detail into analysing, is it a good idea? Do we need to restructure it? It can still have a lot of benefits. It can actually be something worth targeting. But you have to be very aware of that mismatch.
So we would often be asked to look at well, is this trust going to be see through or not in the UK, as what we call a bare trust. And sometimes we’re able to actually give quite a confident yes, we think that will be. Other times we have to be more careful and not only does it impact the income and capital gains tax treatment, but whether you’ve created a substantive trust, will often have a very significant bearing in the UK because we can apply inheritance tax on the creation of a trust.
I think, Suzanna, moving on to you. But on the way in which trusts are treated under the estates treaty is quite significant.
Suzanna (13:16)
Yeah it is. And I mentioned earlier that the estate tax treaties become even more key after the April 2025 changes. And I know we’ve done other podcasts where we’ve talked about those changes in more detail. So, if you’re not familiar, maybe watch one of those rather than me going into lots of detail now. But I think it is worth just noting that in light of those changes, the general position is that a substantive trust, and not a bare trust as the type that Ed was just mentioning, but a substantive trust, now generally follows the tax of its settlor in the UK.
So, for example, if you have created a trust when you’re not a long-term resident, there may not have been any entry charges, for example. But once you become a long-term resident, the standard position is at that point, and going forward, that trust will be within the IHT net and they’ll be ongoing trust charges and potentially charges within your estate as well.
And the reason the UK-US estate tax treaty is so significant in this regard is that in certain circumstances, the treaty can protect trusts that are created by, a US domiciliary, under the terms of the treaty, on an ongoing basis. So, they are not caught within those IHT charges, even once that individual does become a long term resident in the UK and so they can effectively get the treatment we used to be able to get under the old excluded property rules, but continue to get that treatment.
It is worth noting, though, that you can only get that treatment if you’re both a US domiciliary and not a UK citizen at the point that you establish that trust. And so, for that reason, again, citizenship is key. And another point that’s just worth mentioning is that ideally, if you’re going to try and take advantage of the treaty, it’s preferable to have created the trust either, ideally before you’ve even moved to the UK from the US, but if not as early as possible after the move, because, in light of the way the duty works and just in terms of not having to then look at those kind of tiebreaker provisions and work out where there’s any risks, you could be UK domiciled. It’s much cleaner that way. So, it is a really valuable planning tool, but is something that needs to be looked at as soon as possible.
Helen (15:31)
So, something for clients really bear in mind if they meet those criteria.
Suzanna (15:33)
Yeah.
Helen (15:34)
Excellent.
And then in terms of any other lifetime planning opportunities, what are the things that should be considered, and also possibly what are the things that should be avoided for US-UK clients?
Ed (15:44)
So, we’ll come back to this theme a lot of trying to align the taxation and avoiding lifetime planning that has mismatched taxation. Family investment companies are a hot topic in terms of becoming more and more popular. Lots of clients will have heard of them or maybe been suggested them. They don’t tend to work for US persons. The key issues the PFIC rules in the US, which are – we won’t go into detail here – but can have a really negative tax impact on a family investment company which has US persons involved. So generally speaking, if any of the individuals who might otherwise have had an interest in that kind of vehicle have a US person status, we will quickly kind of discount that as an option. If people are really keen to have something that’s not a trust, that is still somehow splitting out of control, over assets from the economic benefit Family Investment Partnerships are something that US-UK, families and individuals often do end up looking at. Because they’re a partnership, they are seen as look-through, basically, in both jurisdictions generally. And that’s where you get the aligned taxation.
So it’s not like you’re not going to pay tax, but you will at least pay tax on pretty much the same thing in both jurisdictions. And therefore you should get the benefit of the credit system. So they can be very attractive in principle. You have to be careful putting them in place because the UK system can see them as Collective Investment Schemes, which has various both regulatory implications potentially, but also actually has an impact on enforceability of certain provisions. You have to be very careful with that. And also, we in the UK have the settlements regime and you can find if you have a Family Investment Partnership with minor children having an interest, that their interest, as it were, if that generates income and gains that those can be attributed in some way, shape or form to the older generation who have put that in place. So there’s kind of careful planning around them, but in principle they can be quite effective lifetime planning vehicles.
Suzanna (17:45)
Yeah. And I mean, I think it’s also always worth thinking about the really simple stuff. So as we would with UK clients, gifting is something that’s always worth considering, rather than some of the complexities of trusts and FICs and PIPs, and all the rest of it. But you probably- there’s a theme developing I know- but the US and UK rules are quite different and so you do have to navigate through the rules, but it is possible.
So, in the US there’s a lifetime exempt amount that you can give. And it’s currently, it changes year by year, it’s currently 15 million. So it’s pretty substantial. But gifts that you’ll make during lifetime can start eating away and using up that overall exempt amount. Whereas in the UK we have what the US would regard as a tiny – well, we all regard as a tiny – amount of 325,000 that you can leave to anybody free of UK inheritance tax. But unlike the US, if you make gifts in your lifetime, if you survive those gifts, and I’m assuming here that they’re just gifts to individuals, if you make those gifts and survive seven years and you’re not still benefiting from what you gave away, then that value can leave your estate completely. So, you could have a situation where you’ve given away many millions in your life. But then as long as you survived that seven-year period, that’s outside of your estate.
So, they are quite different rules, as you can see. But there is things that, you know, you can bear in mind with, with both to sort of try and marry them. So, in the US, for example, it’s possible to give 19,000 USD per year to anybody, and that’s per person. So, you could make gifts to 10/15 family members of 19,000 per calendar year, without that using up any of that lifetime, exempt amount that referred to from a US perspective.
It’s also possible, when we look at this sometimes where we’ve got mismatch between a couple’s domicile, it’s actually possible for a US person’s spouse to make just under 200,000, dollars of gifts to the to the non-US person spouse, because otherwise there’s the limited spouse exemption. And, if you then marry up, for example, the 19,000 gifts with our UK rules, whether that’s as a PET with a seven year rule, providing potentially takeout insurance to cover the risk, or, if you’ve got an individual with significant income, we’ve got an exemption where if you’re making gifts out of your surplus income, effectively, those are not even on the clock for the seven years. So, if you have someone with a very high income, they can make 19,000 gifts, potentially to a lot of different family members using up that surplus income and potentially not have an exposure in the US or the UK. So gifting is still something that’s very much worth considering, but it just needs that little bit of extra careful planning to make sure that you’re not, sort of, the mismatches don’t cause problems.
I think one of the other points I said I’d just briefly touch on was, property rule, because we find that that, sort of, purchases of properties in the UK do quite often create issues for US, persons moving here. Again, the rules aren’t aligned. So in the UK, if you acquire your main residence when you later come to sell it, there’s no capital gains tax because you can get principal private residence relief. But that’s not a thing in the US. And indeed the other issue is it will be a currency gain point potentially. So, when you sell, in due course, you may find that you’ve made a significant gain in currency terms that you end up having to pay tax on in the US, even though in actual terms the gain wasn’t as substantial. There’s not to some extent there’s, there’s little it can be done around that, albeit that in those mismatched marriage situations we would often see the UK person/spouse, acquiring the UK property, not the US person to mitigate those issues.
It’s also just worth bearing in mind that mortgages are also quite problematic for US persons, UK mortgages of property, because every time they make repayments you also have to think about disposals and potential currency gain points. So again, if you don’t need to take out a mortgage, that’s one possibility. Or taking only kind of interest-only mortgages so that you’re not having as many disposals. There’s all sorts of things like that that’s worth talking through, but it is just worth being aware of the complexities there.
Ed (22:05)
And actually to Suzanna’s point on ownership, I mean that that goes for real estate, it goes for lots of other assets as well. You know, if you do have a couple where there’s a mismatch in status, we do quite a lot of planning around who should sensibly own what. Now obviously tax isn’t the only driver there, everyone should be comfortable with whose name is going to be on a particular asset. And one does need to think a little bit about the family law implications. But actually, from a tax perspective, it can be very sensible to have a whole chunk of assets in one particular person’s name and just remove some of that kind of-
Suzanna (22:36)
And in that situation, you might want the US assets to be in the US spouse’s name.
Ed (22:39)
Exactly.
Suzanna (22:40)
So it’s not necessarily in terms of kind of equalising. It might just be the types of assets that it’s worth thinking through.
One other point just to note, is that we sometimes do see people say, oh, can I buy the property in my trust, and or another type of structure? And again, the answer is normally if it’s a property that you’re acquiring for personal use, that’s normally not a great idea. And there’s a whole raft of UK tax implications of that, but it is just always worth making sure that people have thought that through before they try and buy it in their, you know, living trust that they think is fine.
Ed (23:11)
Absolutely.
I think that general piece of looking at, you know, particularly a couple’s assets and working out well, who should own what, but also which of these assets make sense if you’re going to be trying to comply with both the US and UK systems? And I say that probably because lots of specific types of investment in both jurisdiction, which are pitched as tax efficient investments, they will be tax efficient in that jurisdiction, they probably won’t be in the other. In a really simple example, being a UK ISA, which just isn’t going to do anything to protect you from US tax. So, there are lots of examples like that.
But anyone who’s considering moving to the UK from the US or vice versa. There is a very important bit of analysis to be undertaken, which is what do we own? How do you own it? Should we keep all of this? Should we rejig between ourselves? Those are very sensible questions to ask and can save you lots of time and hassle in terms of compliance and planning later down the line.
And another point that actually anyone kind of moving between jurisdictions or with interests in both jurisdictions should bear in mind is their capacity documentation. We in the UK use lasting powers of attorney now to appoint someone to look after affairs if you lose capacity, but that won’t have any impact, generally speaking in the US. So actually if you have US assets, you should have maybe a durable power of attorney, the US equivalent in place or indeed the US equivalent of our kind of health and welfare documents which allow people to make decisions about your healthcare if needed.
So, anyone who’s got interest in both, you should really have capacity kind of documents in both places to make sure, say a court order wouldn’t be required if you were to lose capacity unexpectedly.
Helen (24:48)
That’s a great point.
And the other thing that comes into my mind is life insurance policies, which obviously are very common in both jurisdictions, but particularly so in the US. But clients do need to make sure that their documentation is appropriate across jurisdictional context. And we see when clients, particularly when they moved to the UK with the US policy, we need to make sure that it’s not what we call a Personal Portfolio Bond from UK perspective, which can cause significant tax implications if they continue to hold it. And it can also catch people out because the way it’s assessed, the year in which it assessed is an insurance year and it’s not that doesn’t align to a calendar year, or a tax year, or any other form of year which they might be expecting. And so people really do need to look at those, ideally before they move. But if not, very, very soon after they move.
And they also, I suppose, need to check on the other side for UK clients who have maybe used insurance policies and very common in the UK, we would write them into trust for inheritance tax purposes. If they then move to the US or have US beneficiaries, for example, the sorts of trusts we ordinarily use might not be appropriate. And so, you need to check that the wording is going to work for their circumstances.
Ed (25:59)
I suppose for premiums as well, going back to Suzanna’s point about gifting, you know, making sure you’re paying those premiums is not somehow triggering a tax. You do have to look at both the US and UK gifting rules to check that aligns.
Helen (26:09)
Yeah, absolutely.
And I suppose considerations about life insurance take us quite nicely on to wills and estate planning and, and what happens on death. So, I think let’s look at this from a practical point of view. What are the practical considerations for clients that are US and UK connected? Who are thinking about their wills and their estates and how best to deal with them?
Ed (26:30)
Well, maybe a bit of good news in terms of although we’re going to say many times the US and the UK have very different rules, you can at least have one will, and in fact you often it’s easier to have one will, dealing with both a US and your UK estates. That’s distinct from the capacity documents for example, where you should definitely have one in each jurisdiction so you can have that single will. But whenever we’re helping US-UK clients with estate planning, there are basically two core questions we’re trying to work out the answer to. So there is, is there a mismatch, if it’s a couple, of tax status between the two of them? And if there is that mismatch is the total value of the estate in either person’s hands going to exceed the US exempt amount, which at the moment sits about $15 million. And I’ll let Suzanna explain what happens if we get the answers yes to both of those.
Suzanna (27:16)
Yeah. And I guess just briefly, you know, if the value is significantly below the estate tax exempt amount in that scenario, then it just leads us to focus on the UK tax implications, because as I said earlier, about 325,000 and there’s a limited spouse exemption potentially as well where spouses don’t have the same status. So, it does lead us to focus a little more on the on the UK. If you are above, so for example, if you’ve got a situation – just to bring it to life – of a US spouse that has substantial assets, say 50 million US dollars of assets, and then you’ve got a non-U.S. person/spouse, and you’re then talking through what to do in that situation. If they just left everything from the US spouse to the UK spouse on the first death, then you’ve got the worst of all worlds. The thing that we always want to avoid, because you’d get probably a full spouse exemption in the UK, it might require some elections, but you would probably be able to stretch it such that there’d be no UK tax on that situation. But there would be tax in the US above the available lifetime amount, and that could be 15 million or less depending on lifetime gifts. So, in that situation there are tools that can be used.
And when we’re working with US lawyers, a solution that will often be put forward is a Qualified Domestic Trust that will be included in the will, often referred to as a QDOT and effectively it’s a type of trust that can obtain the spouse exemption in both the US and the UK. It doesn’t stop the tax from being payable. I think that is an important point. It just defers it to the death of the survivor of the spouses. So, in that situation with the US spouse, it would allow them to leave the assets into that QDOT, above the lifetime exempt amount, for their spouse to benefit and then the tax would be triggered on the death of the spouse. But I think you mentioned sort of thinking about it practically, and I do think that is important because when I’ve talked it through with quite a few clients, they sometimes say, look, I don’t really want a QDOT because QDOTs come with complexities. You need to have, for example, a US trustee, and then there’s going to be ongoing tax and sort of filing obligations in terms of marrying the two jurisdictions together.
So, in some cases I’ve had clients that have said, okay, what we want to avoid is any situation where the tax hits at different points in the different jurisdictions. So I don’t want to leave everything to my spouse, my UK spouse on my death, trigger tax in the US above the lifetime exempt amount, not in the UK, but then on the second death there’ll be tax in the UK. And so then we’ve got these two substantial tax charges with no credit. But what they will sometimes say is okay, my spouse doesn’t need more than the 15 million, particularly if I’ve done some gifting and planning in my life. So, I’ll leave the US estate exempt amount to my UK spouse, say. And then above that I’ll just send it down a generation immediately and that will trigger tax. But as I said, a QDOT is only really deferring, and there will be tax but it will be tax in the UK and the US at the same point in time.
So, I think that we always think it’s really important to be aware of the tools and to obviously in conjunction with sort of the US firms that we work with to talk the options through with the client. And it may well be in lots of circumstances that are QDOT, is the right tool, or indeed there may be other things that are suggested, but also to make sure that they are aware of all the options and the practical points that they need to be aware of if they go down that route. Because once you’ve established a QDOT and you’ve done, you know, then extracting assets is going to have implications and might mean you can’t get the marrying of the tax charges. So, you sort of need to know what you’re going into. And I think that’s always what we’re focused on doing.
Ed (31:04)
And remembering that, you know, we talk about the US and the UK in this podcast, but the US is a federal jurisdiction with lots of different states, all of which have different estate tax and indeed succession rules. Often people are surprised by how many US states actually have a form of forced airship, but you don’t have complete freedom as to what you leave to whom, and even the UK. I mean, it’s a kind of there’s less differentiation, but if someone’s moved from the US to Scotland and has lots of Scottish assets, the Scott’s system is quite different to other parts of the UK. So there’s a practical point about just being really clear on this is not theoretical or this is how is it going to apply to you, your family and your particular, you know, asset base and working out a system that that will achieve whatever your wishes are there.
And there is quite a bit in both jurisdictions, then of just trying to amend our kind of standard practice to make life easier in the other jurisdiction. A common example of that is you’ll often see in US wills, if they’re just drafted from a US domestic perspective, there’ll be some kind of, you know, effectively lifetime pilot trust and the will kind of pours into that. Now that can work in the UK, but it’s less clear sometimes that our spouse relief, for example, would work because that trust hasn’t necessarily been created on death in the way that our legislation envisages. And so often if we’re helping someone prepare a US-UK will, its just trying to make sure all those little points were making it as easy as possible to process that will in both jurisdictions when the time comes.
Helen (32:36)
Thank you both for those really helpful insights for our UK, US connected clients. To pull everything together, please can I ask you for three main points which you would like clients to take away from this?
Ed (32:47)
Mind if I lead off?
Suzanna (32:48)
Go for it.
Ed (32:49)
Okay.
So number one, as has been made abundantly clear, the US and UK are very different taxing systems and generally the legal systems themselves have surprising differences. But when done well, US-UK planning can put all that together and create an option for a client, or actually we’re having the same thing taxed in the same way in both jurisdictions. You marry it up so that you have the desired effect in both in both places. So good US-UK estate planning can absolutely achieve a, not maybe straightforward, but a unified outcome across the board that can help clients in a practical way, not fall foul of all these myriad traps and tricks.
Suzanna (33:34)
Yeah, I mean, I think very much the similar points there, classic planning in both jurisdictions may need to be adapted to accommodate the other jurisdiction. Trust life insurance, will planning, whatever it may be. There’s plenty of opportunities. But if done poorly, it can cause a lot of problems. And I think alongside that, it’s just always important to bear the treaties in mind, because they can have a significant impact in that wider planning.
Ed (34:00)
And to finish off, I appreciate this is not entirely unbiased as the recommendation, but, taking good advice, taking it as early as you possibly can. As we’ve kind of hinted at, but there are lots of timing points here that we haven’t gone into detail about. And getting timing right on lots of this can be really important. So going to a great advisor a bit late is going to be nowhere near as valuable to a client that’s going to a good advisor early on, and we’d be delighted to help with any UK aspects of this kind of planning.
Helen (34:30)
That’s great. Thank you very much Suzanna and Ed for joining us today.
Suzanna (34:31)
Pleasure.
Helen (34:32)
And thank you for listening to you or watching this episode of Death and Taxes – the Private Wealth podcast from Burges Salmon. If you’d like to learn more about the issues covered in this episode, please do get in touch with us. You can find further insights from the Burges Salmon Private Wealth team on our website at Burges-Salmon.com or on our LinkedIn page. And don’t forget to subscribe to hear about the latest developments in private wealth, trusts, tax and succession planning.
Thank you for listening.
 Thought leadership
22 October 2026
Podcasts
15 October 2026 • 10 min read

Podcasts
1 October 2026 • 10 min read
Thought leadership
28 September 2026
Thought leadership
24 September 2026
Legal updates
9 September 2026
Thought leadership
7 September 2026
Thought leadership
19 August 2026
Want more Burges Salmon content? Add us as a preferred source on Google to your favourites list for content and news you can trust.
Update your preferred sourcesBe sure to follow us on LinkedIn and stay up to date with all the latest from Burges Salmon.
Follow us