This website will offer limited functionality in this browser. We only support the recent versions of major browsers like Chrome, Firefox, Safari, and Edge.

Search the website
Thought leadership

Budget 2026: Key takeaways for private clients
Picture of Edward Hayes TEP
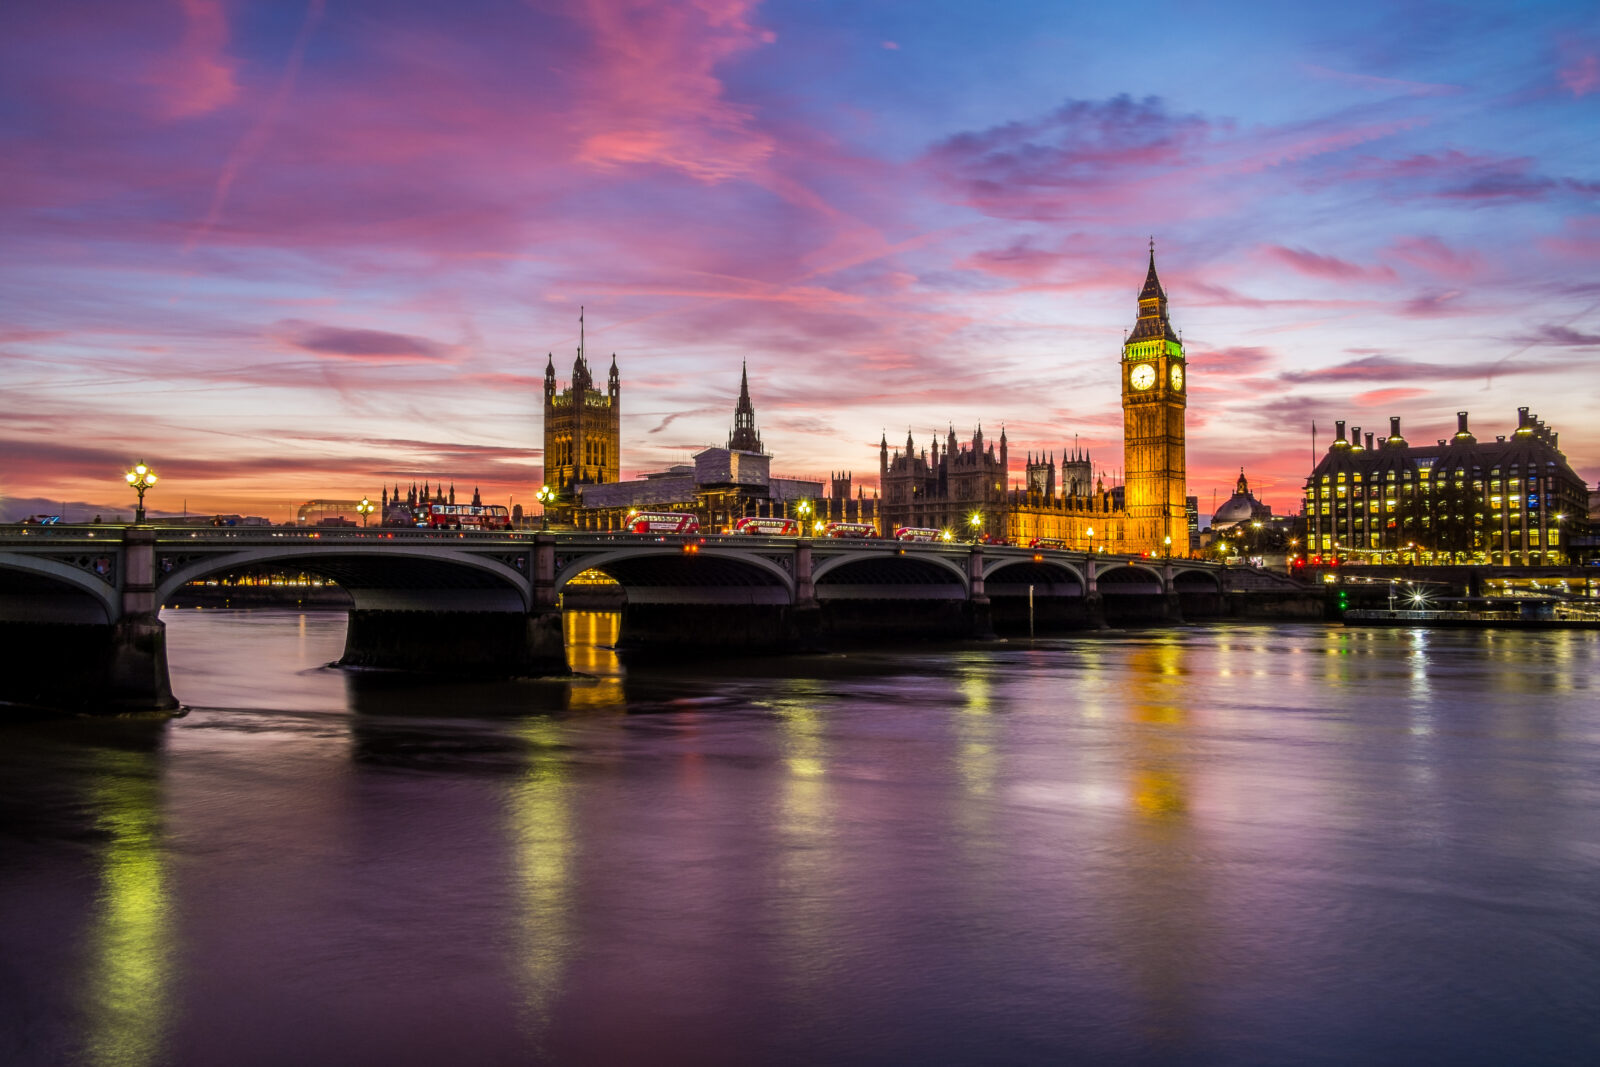
Houses Of Parliament At Dusk.

While some of the more widely anticipated tax changes did not materialise in the Autumn Budget 2026, there are still a number of important developments for private clients to consider. From new measures for entrepreneurs to changes affecting property, trusts and tax compliance, we highlight the key announcements below.

Minimal changes to headline tax rates

  • Rumoured changes to capital gains tax and inheritance tax did not appear.
  • Income tax rates are going up on property and savings income (to a maximum of 49% from 6 April 2027) but are otherwise also unchanged.

Major announcements for entrepreneurs and business owners

  • This currently allows up to £1m of gains realised on the sale of a business to be taxed at 18% rather than 24%.
  • From 6 April 2027 the £1m limit will reduce to £500,000.

New Founders’ Relief:

  • This will more than make up for the restriction to BADR for those who qualify as it applies a 10% tax rate to up to a lifetime limit of £10m of gains.
  • However, the qualification criteria will be much stricter.

The relief is subject to consultation. The conditions below reflect the current proposal.

To be a “Founder” an individual must have:

A company must:

Growth and innovation criteria:
(2 out of 3 to be satisfied)

Owned at least 25% of the business at the outset 

Be trading (or the holding company of a trading group)

Growth in revenue of at least 25% over a three-year period

Held their shares for at least 5 years

Be subject to UK corporation tax (so UK tax resident or operating via a permanent establishment in the UK)

Growth in headcount of at least 25% over a three-year period

Been UK tax resident for at least 5 tax years

Have turnover of at least £10m and at least 15 full-time employees

Incurred at least £1.5m of qualifying R&D expenditure

Property

  • Income tax rates on rental income will increase (to a maximum of 49%) as mentioned above.
  • The new “High Value Council Tax Surcharge” (charged on properties worth over £2million) will feature a 100% premium for properties left empty for 12 months or more.

Trusts

Changes are expected to:

  • How liabilities can be deducted when calculating inheritance tax charges.
  • How capital gains tax exit charges work when trusts migrate (and in particular a helpful relief for trusts which temporarily migrate into the UK).

Other points

  • The Government will push ahead with changing the way in which certain corporate distributions are taxed. Details are still to be confirmed but this could impact a range of structures in due course.
  • There will also be changes to the way in which loans from non-UK resident companies to UK resident individuals are taxed.
  • Anti-avoidance rules for protected cell companies are changing so that they no longer block attribution of gains to shareholders (note this takes effect immediately).
  • A new tax credit is being introduced to mitigate double taxation in relation to “reverse-hybrid” entities (i.e. those treated as opaque for UK tax purposes in the UK but transparent elsewhere) such as US LLCs and French SCIs.
  • HMRC is changing the way it handles compliance for “wealthy taxpayers” (those with income of over £200,000 or assets in excess of £2m).
  • More generally there will be changes to self-assessment taxation, including moves towards smaller but more regular tax payments and changes to obligations to notify HMRC if and when errors in returns are discovered.
  • The Government will continue to monitor the UK’s special tax regime for new arrivals (commonly referred to as the “FIG regime”) to assess its impact.

The impact of these changes will depend on individual circumstances, with further detail on a number of measures still to come. Visit our Budget Hub for the latest analysis and insights from our specialists on Budget 2026 and what it could mean for you and your affairs.

Private client and family law

Explore our full offering and expertise using the link below.

Learn more
Download this guide

Click the button to download a PDF version of this guide.

Download PDF version

Related topics

See more from Burges Salmon

Want more Burges Salmon content? Add us as a preferred source on Google to your favourites list for content and news you can trust.

Update your preferred sources

Follow us on LinkedIn

Be sure to follow us on LinkedIn and stay up to date with all the latest from Burges Salmon.

Follow us